

Based on reporting by GamblingNews →
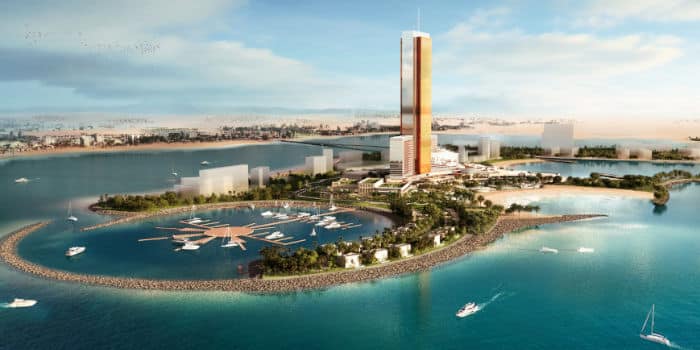
Wynn Resorts' planned integrated resort in the United Arab Emirates is drawing bullish analyst attention as Wolfe Research projects the property could significantly outperform current financial expectations. The Al Marjan Island development, scheduled to open in September 2027 off the coast of Ras Al Khaimah, represents the first licensed commercial casino in the Middle East and carries an estimated development cost of $5.7 billion.
Wolfe Research analyst Peter Supino believes Wynn Al Marjan Island could exceed company forecasts, citing the emergence of high-performing casino markets in comparable jurisdictions. The investment firm projects the resort could generate up to $1.66 billion in annual gaming revenue, with adjusted property EBITDA ranging from $390 million to $570 million annually after management fees. This optimistic outlook underpins Wolfe's 60 percent upside projection for Wynn Resorts shares by the end of 2027, particularly significant given the stock's 37 percent year-to-date decline through October 2026.
The bullish case rests on several structural advantages. The UAE's tourism infrastructure is expanding rapidly, with luxury hotel rooms representing 43 percent of planned additions through 2030 according to Knight Frank. Additionally, approximately one-third of the global population lives within a four-hour flight radius of the country, positioning Al Marjan Island to capture international visitation. Wolfe draws parallels to Singapore, where limited casino supply and strong tourism demand have created two of the world's most profitable gaming properties: Marina Bay Sands and Resorts World Sentosa. Industry projections suggest the UAE could eventually support four to five casino resorts, implying significant early-mover advantages for Wynn's entry.
Wynn's December 2025 projections indicate the property could capture meaningful market share in a UAE gaming market previously estimated to reach $3 billion to $5 billion annually as additional properties come online. Wolfe values Wynn's 40 percent stake at approximately $48 per share, contributing substantially to its $128 price target, which reflects 8.5 times projected 2028 adjusted EBITDA plus the UAE investment value.
However, the outlook carries material risks that investors should weigh carefully. Macau operations face near-term pressure, historically Wynn's most profitable segment. Regional geopolitical tensions present ongoing uncertainty, evidenced by a construction pause in 2026 related to Iran-involved conflict, though work resumed following the March hiatus. The Middle East's volatile political environment could impact visitor flows, regulatory timelines, or operational conditions once the resort opens.
Casino development pipelines globally remain active, with integrated resorts representing significant capital commitments in emerging markets. From a CasinoAdvisor perspective, Wynn's UAE expansion reflects a strategic bet on geographic diversification away from core Asia-Pacific markets. The project's execution and market reception will offer valuable data on casino demand in regulated Middle Eastern markets, potentially signaling broader regional interest in commercial gaming infrastructure. The September 2027 opening timeline places this property at the forefront of Middle East casino development and could reshape competitive dynamics across luxury hospitality in the region.
Source
GamblingNewsRelated stories
DraftKings Pledges $100K to Ontario Food Banks Through Thanksgiving Betting Campaign
Latin America iGaming operators need speed and flexibility in platform selection
Midnite Secures NFL Betting Partnership in UK and Ireland Through 2029
Entain Expands New Zealand Footprint Ahead of 2027 Online Casino Market Launch
More on CasinoAdvisor