

Based on reporting by Casino.org →
The United Kingdom's gambling market demonstrated solid expansion in the fiscal year ending 2026, with gross gaming yield (GGY) climbing 4.4% to reach GBP 17.5B. This growth trajectory underscores the ongoing structural shift within Britain's betting and gaming landscape, where digital channels continue to outpace traditional retail operations.
The online sector's dominance as the primary growth engine reflects broader industry trends observed across mature gambling markets. As consumer preferences increasingly favor convenience and accessibility offered by digital platforms, operators have invested heavily in technology infrastructure, mobile optimization, and user experience enhancements to capture this expanding segment. The UK market, regulated by the UK Gambling Commission (UKGC), has maintained a competitive environment where multiple licensed operators vie for market share, contributing to innovation and consumer choice.
This FY2026 performance data arrives at a critical juncture for UK gambling regulation. The sector has faced heightened scrutiny regarding affordability checks, safer gambling measures, and responsible operator conduct. The UKGC has signaled intentions to strengthen protections for vulnerable consumers while maintaining a framework that allows legitimate operators to function competitively. The 4.4% expansion suggests that the market has absorbed recent regulatory adjustments without significant contraction, though stakeholders continue debating whether current safeguards adequately balance consumer protection with industry viability.
For operators and investors, the GBP 17.5B market represents substantial opportunity, though the growth rate of 4.4% reflects moderation compared to pandemic-era surges. This normalization is expected as markets mature and regulatory intensity increases. The continued primacy of online channels also highlights the declining relevance of brick-and-mortar gambling establishments in revenue generation, forcing traditional venues to adapt or exit the market.
The UK gambling market's size and regulatory maturity position it as a bellwether for other European jurisdictions. As operators across the continent navigate divergent regulatory frameworks (from Netherlands' iGaming liberalization to stricter German controls), the UK's ability to generate sustained growth under robust oversight provides a model for balancing public health objectives with economic activity.
From a market monitoring perspective, the FY2026 data underscores the UK's position as one of Europe's largest gambling markets. With online channels driving expansion, the competitive landscape continues to favor operators with sophisticated technology platforms and omnichannel capabilities. The 4.4% growth, while solid, suggests the market has reached a maturation phase where future gains will increasingly depend on market share transfers rather than wholesale consumer acquisition, intensifying competition among established licensees.
Source
Casino.orgRelated stories
New York Sportsbooks Post Record NFL Opening Week Handle Amid Prediction Market Competition
NFL Week 1 Ignites Sports Betting Surge, GeoComply Records 99.8M Geolocation Checks
Buffett's Retirement Caps Decades-Long Critique of America's Gambling Culture
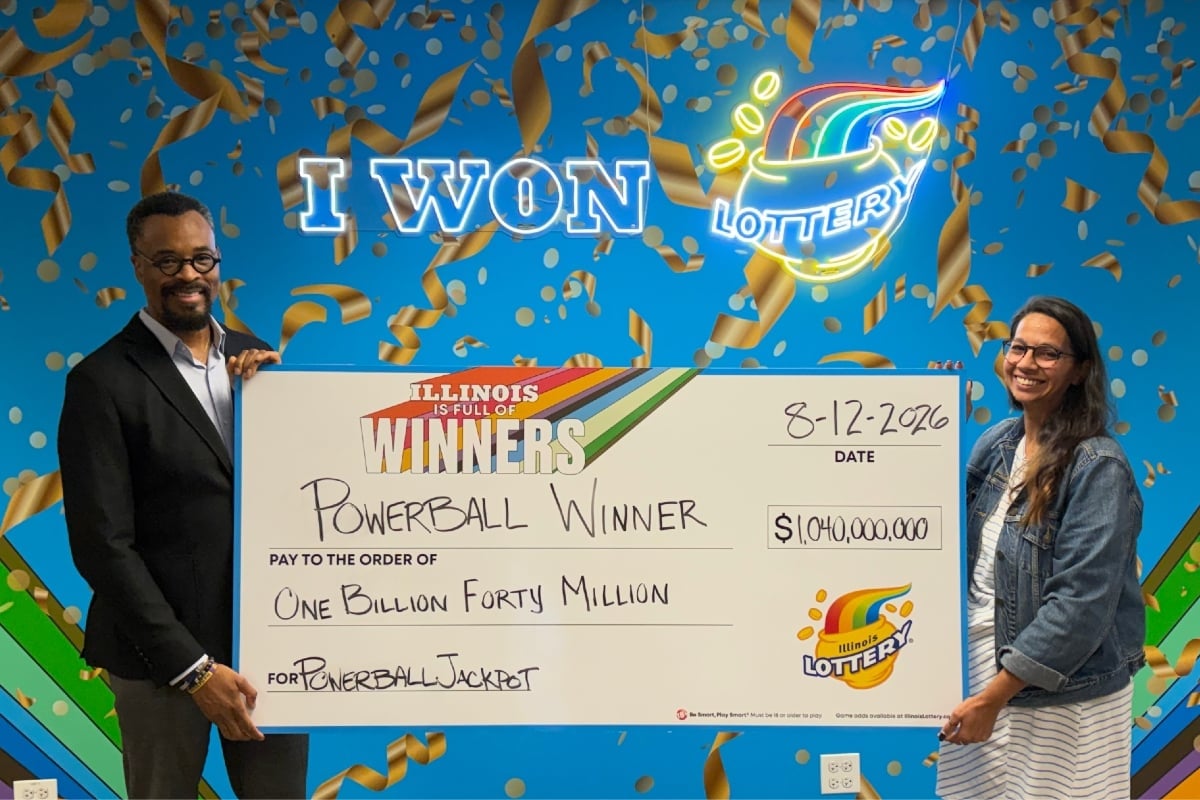
Illinois Powerball Winner Claims $1.04B Jackpot, Opts for $261.5M Cash Payout
More on CasinoAdvisor