

Based on reporting by Casino.org →
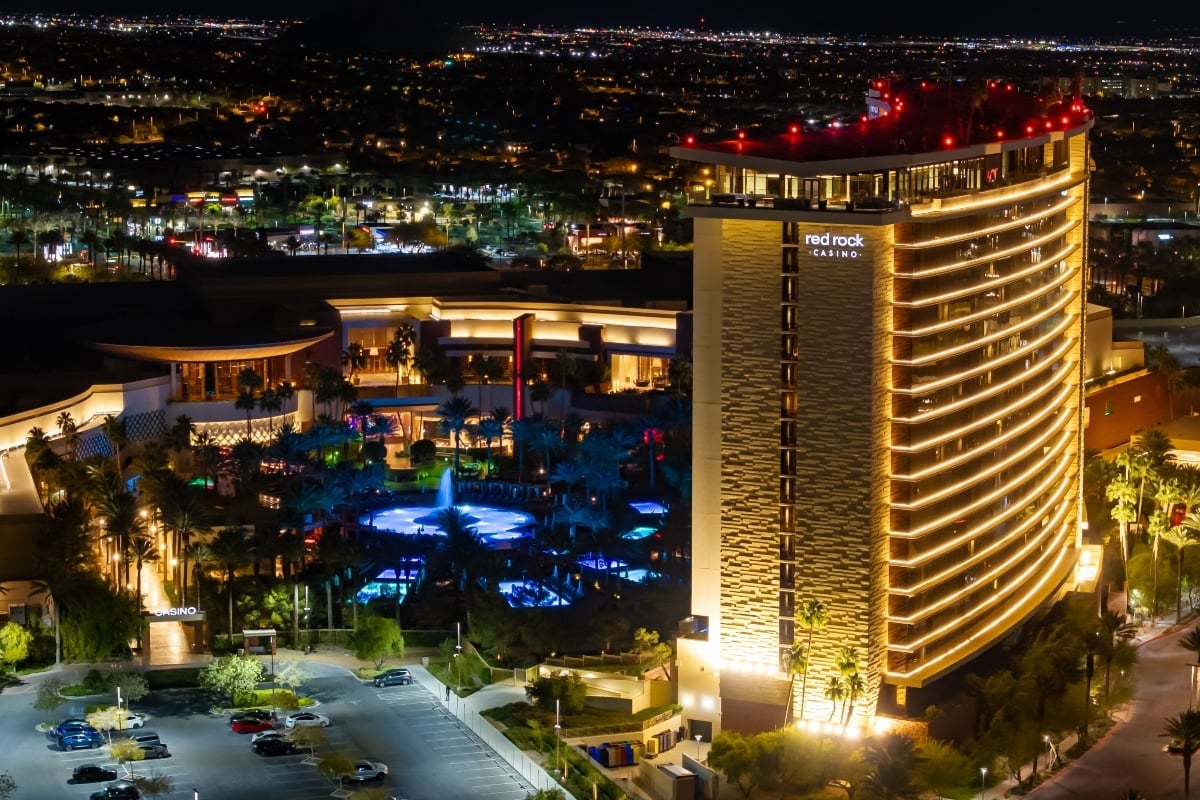
Red Rock Resorts (NASDAQ: RRR) is navigating a challenging year marked by construction disruption at three of its Las Vegas Valley properties, yet a coalition of high-profile investors and Wall Street analysts are maintaining their bullish stance on the operator's stock and long-term prospects.
The company's year-to-date stock performance has been pressured by ongoing capital investments at the Durango Casino & Resort in Southwest Las Vegas, Green Valley Ranch, and Sunset Station. These enhancement initiatives have created near-term headwinds that have dinged financial results and contributed to a 10 percent decline in the stock this year. However, the prevailing narrative from company management, institutional investors, and sell-side analysts frames this as a classic "near-term pain, long-term gain" scenario.
Ron Baron, founder of Baron Capital and a long-standing Red Rock investor, reiterated his confidence in the operator in recent commentary to shareholders of the Baron First Principles ETF (NYSE: RONB), the firm's flagship exchange-traded fund. Red Rock represents the fund's tenth-largest holding at 2.61 percent of the portfolio. Baron praised Red Rock's strong balance sheet and increased liquidity, stating that the stock remains attractive relative to what the business can become over time. He noted that construction disruption dissipated during the second quarter, allowing investors to look ahead to the benefits of the company's recent property investments, which should translate to increased earnings and cash flow while supporting continued reinvestment and shareholder returns.
The sell-side consensus reinforces this optimistic outlook. Texas Capital analyst David Bain recently initiated coverage of Red Rock with a "buy" rating and a $72 price target, implying potential upside of nearly 33 percent from current trading levels. Bain's thesis centers on Red Rock's strategic positioning in the booming Las Vegas locals market, where the operator has demonstrated a willingness to invest in property enhancements while maintaining strong returns on those investments.
A particularly compelling element of Bain's research highlights Red Rock's substantial real estate holdings as a potential catalyst. The operator's approximately 442-acre Nevada land bank, combined with its track record of generating 20 percent-plus internal rates of return on greenfield projects, positions the company for what Bain characterizes as an "unmatched, long-term growth pipeline." Bain anticipates a new project announcement by the first half of 2027, which he views as a near-term stock catalyst.
Red Rock's appeal to both the buy-side and sell-side reflects broader confidence in the operator's execution capabilities and its exposure to one of the nation's most dynamic casino markets. The Las Vegas area is experiencing significant population growth, and Red Rock has been successfully capturing increased wallet share from the local player segment. Baron Capital's decision to maintain Red Rock as its only gaming stock holding in the RONB ETF, while holding Wynn Resorts in another fund, underscores the firm's confidence in Red Rock's distinct investment merits. For CasinoAdvisor, this convergence of institutional support and analyst optimism suggests the market may be underweighting Red Rock's post-construction earnings potential and the growth optionality embedded in its real estate portfolio.
Source
Casino.orgRelated stories
DraftKings Positioned to Generate $57M in NFL Prediction Market Fees This Season

Wynn Resorts Issues $900M Bond Sale to Refinance Las Vegas Debt Maturity
Playtech Posts 77% EBITDA Growth on Hard Rock Digital Momentum in North America
Las Vegas targets Australian market with $1.45M campaign as Qantas launches nonstop service
More on CasinoAdvisor