

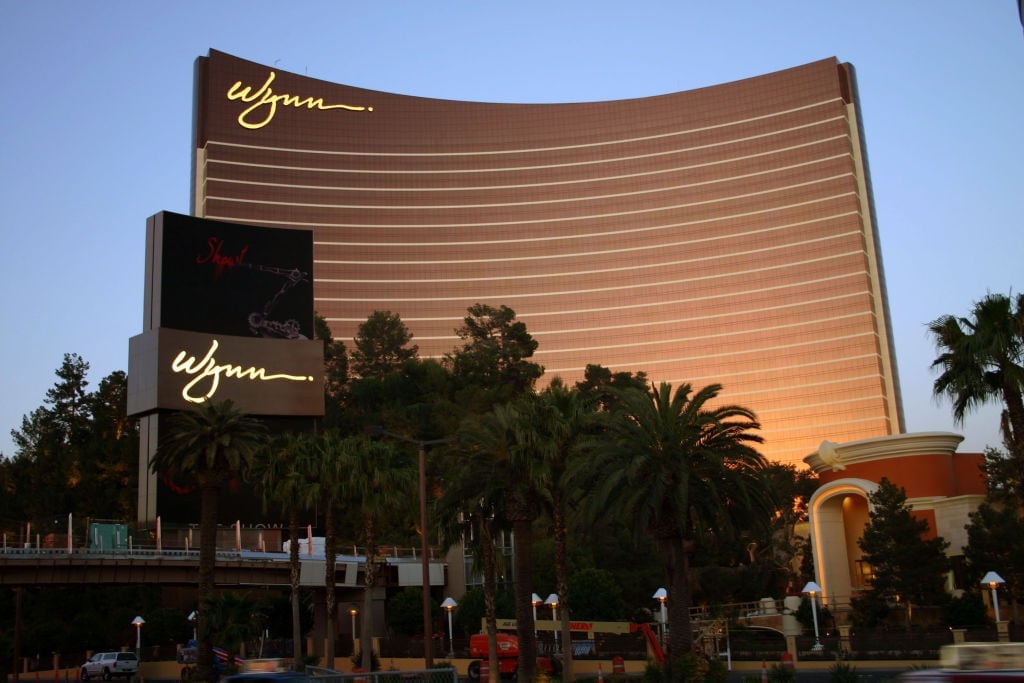
Based on reporting by Casino.org →
Wynn Resorts' stock performance has deteriorated sharply in 2026, with shares off 29.23% year-to-date and trading near 52-week lows. According to a recent JPMorgan report, two significant factors are weighing on investor sentiment: tepid recovery in Macau gaming revenue and ongoing concerns about the company's ambitious United Arab Emirates expansion project.
Macau, which represents Wynn's largest market by earnings and revenue, has proven a particular disappointment following the World Cup concluded in July. Many in the investment community had speculated that the tournament's end would spark a rebound in gaming activity after the event depressed traffic in June and July. However, that anticipated recovery has not materialized. August data showed gross gaming revenue in the Chinese casino enclave declined 1.2%, and analyst Daniel Politzer noted that "post-World Cup demand rebound appears short-lived." The softness has extended into September, according to multiple sell-side observers, challenging the narrative that seasonal recovery would restore vibrancy to the world's largest casino market.
Parallel to Macau challenges, geopolitical instability is creating uncertainty around Wynn's flagship international development. Wynn Al Marjan Island, a $5.1 billion resort under construction in Ras Al Khaimah in the UAE, has emerged as a significant point of investor anxiety. Earlier in 2026, Wynn disclosed that the Iran conflict would cause a "modest delay" to the project timeline. While the company subsequently guided to a mid- to late-2027 opening, which initially appeared to stabilize investor perception, concerns have resurfaced. Politzer notes that market participants view the ongoing Iran conflict as presenting "significant risk" to the venue's opening timeline, operational performance upon launch, and the ramp-up process. Adding to the disconnect, JPMorgan observes that equity markets currently assign "little/no equity value" to the UAE project, suggesting investors may be heavily discounting or outright ignoring the asset's long-term contribution to shareholder returns.
From a valuation standpoint, Wynn stock does not appear to offer a compelling discount despite recent weakness. The stock trades at 9.7x estimated 2027 enterprise value-to-EBITDA, only marginally below the three-year average of 9.8x. This suggests the market may already be pricing in concerns about both Macau and the UAE development, leaving limited room for multiple expansion even if sentiment improves.
Macau's structural outlook adds another layer of complexity. CLSA, in a separate report, projects Macau GGR will increase just 2.4% in the coming year, citing insufficient macroeconomic support despite cyclical tailwinds such as low year-ago comparisons and potential mean reversion in VIP win rates. This cautious stance indicates that even optimistic analysts do not expect near-term acceleration in the market that supplies most of Wynn's profitability.
For CasinoAdvisor's coverage of global operators, the Wynn situation underscores how regional concentration risk and geopolitical exposure can materially pressure valuation multiples independent of underlying business fundamentals. As the industry spans multiple jurisdictions and markets, operators with heavy geographic concentration face outsized vulnerability to localized demand disruptions and international tensions.
Source
Casino.orgRelated stories
Kenneth Dart Pauses Flutter Entertainment Purchases After Year of Aggressive Accumulation
Genius Sports Positioned as Key B2B Winner in Prediction Markets Expansion
NFL Week One Delivers Bettor Bonanza as Sportsbooks Navigate High-Scoring Games
Raiders' Kubiak Era Draws Heavy Nevada Betting Action as Sportsbooks Assess NFL Season Liabilities
More on CasinoAdvisor