

Based on reporting by iGaming Business →
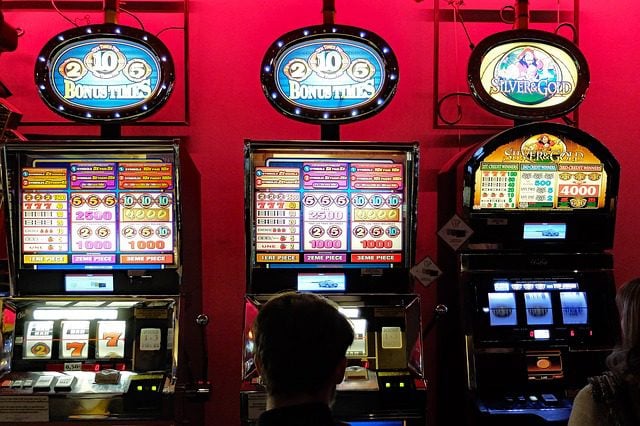
The UK's high-street gambling sector faces an internal credibility crisis as potential machine games duty (MGD) increases threaten operational viability across multiple verticals. With a possible doubling of MGD from 20% to 40% under consideration, bookmakers and adult gaming centres (AGCs) are fragmenting their defensive arguments in ways that industry veterans warn could backfire strategically.
Regulus Partners modelling estimates that a doubling of MGD could eliminate approximately 4,000 betting shops, reducing the sector to around 1,500 locations and costing 28,000 jobs. The analysis suggests the average betting shop generates annual net cash contribution of roughly 44,000 pounds after all operating costs, with a doubling of MGD adding approximately 45,000 pounds in annual costs. Beyond the immediate financial impact, the consultancy forecasts that betting-shop MGD receipts would decline by around 32% to 155 million pounds, potentially undermining the Treasury's presumed revenue-raising objective.
The damage extends beyond bookmakers. Bingo operators have publicly warned that machines represent critical secondary income. Bingo Association CEO Nicole Barrett and Buzz Bingo CEO Dominic Mansour have separately cautioned that even modest MGD increases could render significant portions of their operations unviable.
However, the sector's response reveals dangerous fault lines. Some industry figures, including consultant Vaughan Lewis writing in The Racing Post, have argued that AGCs could better absorb duty increases than bookmakers, since arcades do not contribute to racing's levy and media rights payments. This distinction has created an implicit hierarchy suggesting certain venue types merit protection over others.
Nick Rust, former British Horseracing Authority chief executive and betting industry executive, characterizes this approach as strategically counterproductive. "Whenever you start attacking a subsector within your own industry, you have to think about what that looks like. Whataboutery isn't going to help anyone," Rust stated. He emphasizes that public perception does not differentiate between high-street locations offering identical machines, and that sectoral infighting undermines collective defence.
An anonymous industry consultant more directly identifies the logical trap: if bookmakers argue that AGCs can withstand 40% duty, they are essentially conceding the tax's acceptability. "If betting uses the argument that arcades can withstand this, then that is saying raise the tax," the consultant explained. "It sounds like special interest pleading and not a real argument."
Rust draws historical parallels to the fixed-odds betting terminal (FOBT) controversy, when amusement industry body BACTA attacked bookmakers. That divisive approach, he suggests, ultimately weakened both sectors' defence positions. Attacking other licensed gambling venues now offers no public relations advantage and risks demonstrating internal disagreement to policymakers.
Beyond revenue considerations, Rust highlights broader high-street implications. He describes watching local betting shops close incrementally and warns that further closures would eliminate another meeting place as pubs and other community institutions retreat. He also flags a regulatory concern: that closure of licensed premises could displace customers into unlicensed environments, a consequence the anti-gambling lobby often fails to address.
The stronger unified argument concerns economic fundamentals: what receipts the duty increase would actually generate relative to closures it would trigger, and where displaced customers would ultimately congregate. A fragmented sector presenting inconsistent arguments about which venues should survive ultimately weakens the case that the tax itself is economically counterproductive.
Source
iGaming BusinessRelated stories
EU and UK Launch Antitrust Probes into Sportradar's Sports Data Monopoly
Malta Media Journalist Michael Schmitt's Identity Questioned After AI Avatar Confirmation
Google Adds Dedicated Prediction Market Section to Ad Policies
IG Group CEO Questions Prediction Market Volume Metrics as Supreme Court Clarity Looms
More on CasinoAdvisor