

Based on reporting by Casino.org →
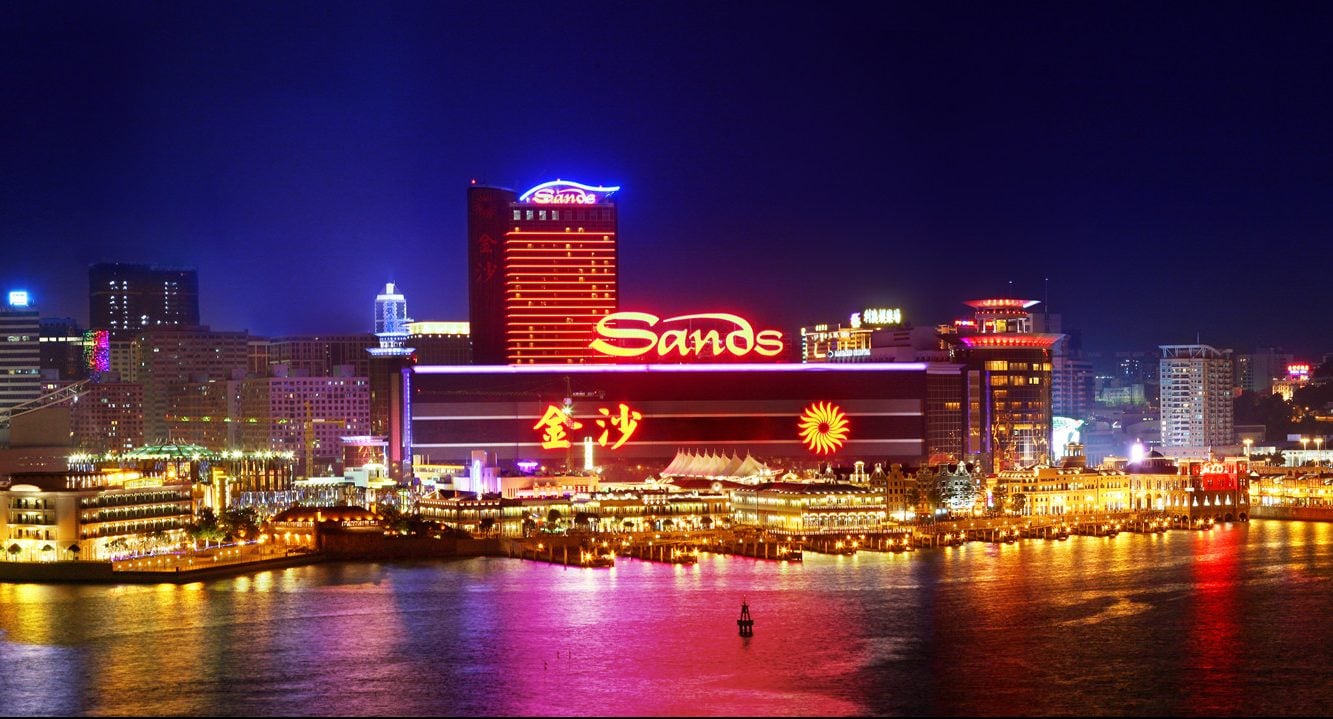
Las Vegas Sands has endured a punishing year in public markets, with its stock shedding 40% of its value amid persistent softness in Macau gaming revenues. But a fresh bullish call from Texas Capital analyst David Bain suggests the market may be significantly undervaluing the world's largest casino operator by market capitalization.
Bain initiated coverage with a buy rating and $59 price target, implying more than 50% upside from recent trading levels. The core thesis rests on several pillars: a total shareholder yield of 13.1% that ranks in the top 2% of global equities, aggressive and accretive share repurchases executed at single-digit enterprise value-to-EBITDA multiples, and a 20% dividend increase announced in October that affirms management's commitment to returning capital.
The analyst characterizes Sands as a 'corporate cannibal' for its opportunistic buyback activity and its strategy of acquiring publicly traded shares of Sands China, its Macau subsidiary, pushing ownership past 75%. Bain argues this represents a 'backdoor repurchase' that consolidates the eventual Macau cyclical rebound at a steep discount, positioning shareholders to capture explosive earnings-per-share upside when high-margin mass-market EBITDA accelerates.
The Macau question looms largest for Sands investors. The jurisdiction remains a critical earnings driver, with Sands China operating five integrated resorts there. Gross gaming revenue growth has been anemic, weighed down by weak consumer sentiment on mainland China. However, Bain argues the weakness is cyclical rather than structural, driven by temporary dampening of visitation desire rather than fundamental alteration in the aspirational appeal of Macau's casino resorts to Chinese nationals.
The analyst also highlights what he calls the market's failure to properly 'unbundle' Marina Bay Sands in Singapore from Sands' Macau exposure. Singapore's integrated resort is a force unto itself, generating more earnings and revenue than some multi-casino U.S. markets. Bain argues Marina Bay Sands operates as an 'unassailable sovereign duopoly' producing $2.5 billion-plus in annual property EBITDA with nearly 50% EBITDA margins, unmatched pricing power, and exclusive, entrenched concession license longevity. He suggests the Singapore property warrants a 12x-14x infrastructure-like valuation multiple, reflective of its return on invested capital and free cash flow visibility.
The analyst's framework assumes that Sands' capital return programs, combined with the eventual Macau recovery and proper recognition of Singapore's standalone value, should compound per-share intrinsic value and deliver equity upside when margin expansion materializes. The thesis essentially positions Sands as a capital-disciplined operator leveraging near-term weakness as a buying opportunity, with significant asymmetric return potential tied to cyclical recovery in one of the world's highest-margin gaming markets. For CasinoAdvisor's coverage of global operator positioning and capital allocation strategies, Sands' shareholder return framework and geographic diversification across Asia and North America represent a noteworthy case study in how operator strategy adapts to regional market cycles.
Source
Casino.orgRelated stories
Fontainebleau Taps Margaritaville Brand to Revamp Florida Slots Venue
VICI Properties Positioned as Potential Buyer for Churchill Downs Regional Casino Divestiture
Better Collective Posts Record Q3 Revenue as Leadership Restructures Around Brazil Ban
Hard Rock Las Vegas Guitar Hotel Remains on Track for Late 2027 Opening
More on CasinoAdvisor